Reading the package properly
We go through what has been offered, which parts are statutory and which are at the employer's discretion, and what each one means for you before you agree to it.
A termination package is often the largest single payment somebody ever receives, and it arrives at the worst possible moment for clear thinking. There are decisions inside it that cannot be undone, and an income to plan for between now and whatever comes next.
A no-obligation, free discovery call with a Pathway planner. Nothing is sold on it.

A redundancy package is usually more than one thing, and the parts are treated differently. The statutory element has its own qualifying conditions: they include 104 weeks of continuous employment with the same employer, employment fully insurable under the Social Welfare Acts, the job no longer existing, and the employee being over 16.
The statutory amount is two weeks' pay for every year of service over age 16, plus one additional week's pay, and that calculation is subject to a €600 per week limit, using normal gross weekly wage or an average where there is no normal weekly wage. For most people that means the statutory part is a smaller share of the package than they expected, and the rest is whatever the employer has agreed on top.
That extra part is where the treatment matters. Revenue's position is that redundancy or retirement lump sums may be partially or totally exempt from Income Tax, PRSI and USC, while a contractual lump sum is taxable in full and does not qualify for exemption or relief. Which side of that line your payment falls on depends on how it arises, and it is worth establishing before anything is signed.
Underneath all of it sits a decision people make far too quickly: whether to give up pension lump-sum rights at retirement in exchange for a larger tax-free amount today. It can be the right call. It cannot be reversed, which is why it belongs in a proper pension conversation rather than a rushed one.
Not sure which part of the package is which? That is exactly what the first call is for.
Four things worth settling before you sign anything.
We go through what has been offered, which parts are statutory and which are at the employer's discretion, and what each one means for you before you agree to it.
Some of the more generous exemptions come at the cost of pension lump-sum rights later. Trading a future entitlement for cash now is sometimes right and sometimes badly wrong, and either way it is permanent.
Between jobs, a lump sum is an income rather than a windfall. We work out what it has to cover, for how long, and how much of it should stay liquid, using cashflow modelling so you can see it rather than guess at it.
Death in service cover, income protection and scheme benefits usually end with the employment, and people discover that at the worst possible time. We check what is going and what should replace it.
A short call will tell you which of these decisions is actually live for you.
Pathway was built by two planners who believe advice should be clear, honest and genuinely on your side.
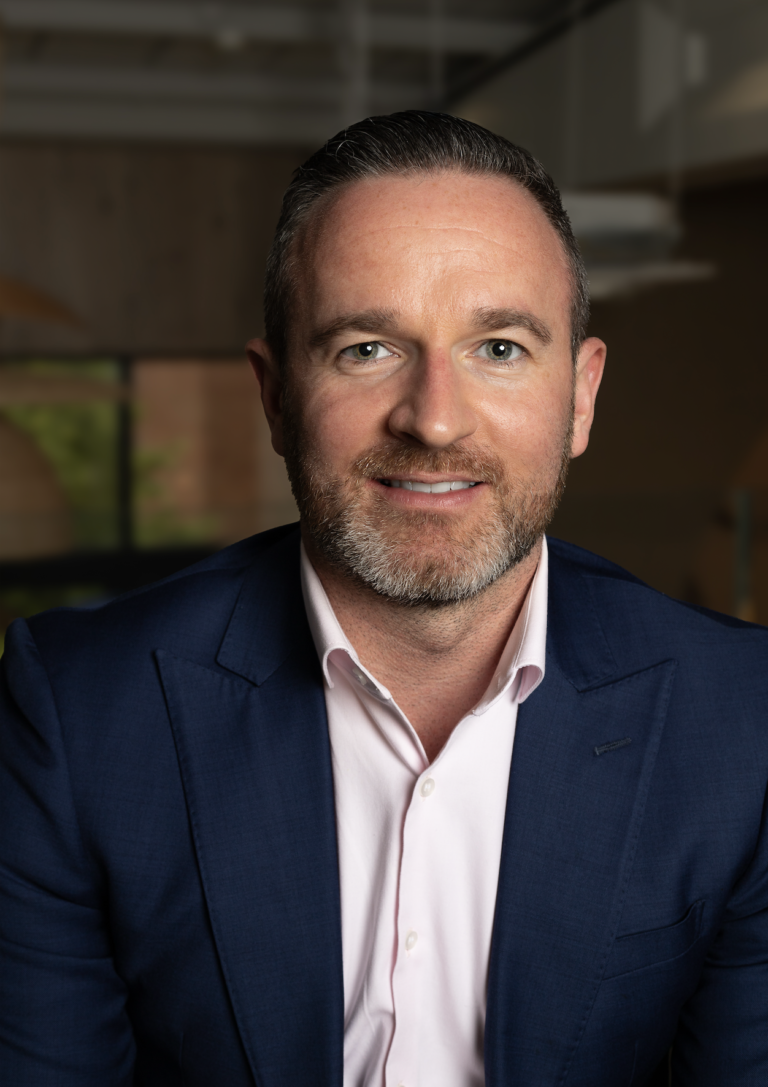
Director & Financial Planner
QualificationsCFP®, BBM, QFA, RPA, SIA
Paul is driven by making a tangible difference in clients' lives, and takes real satisfaction in knowing his work supports individuals and their families through decisions that are rarely straightforward.
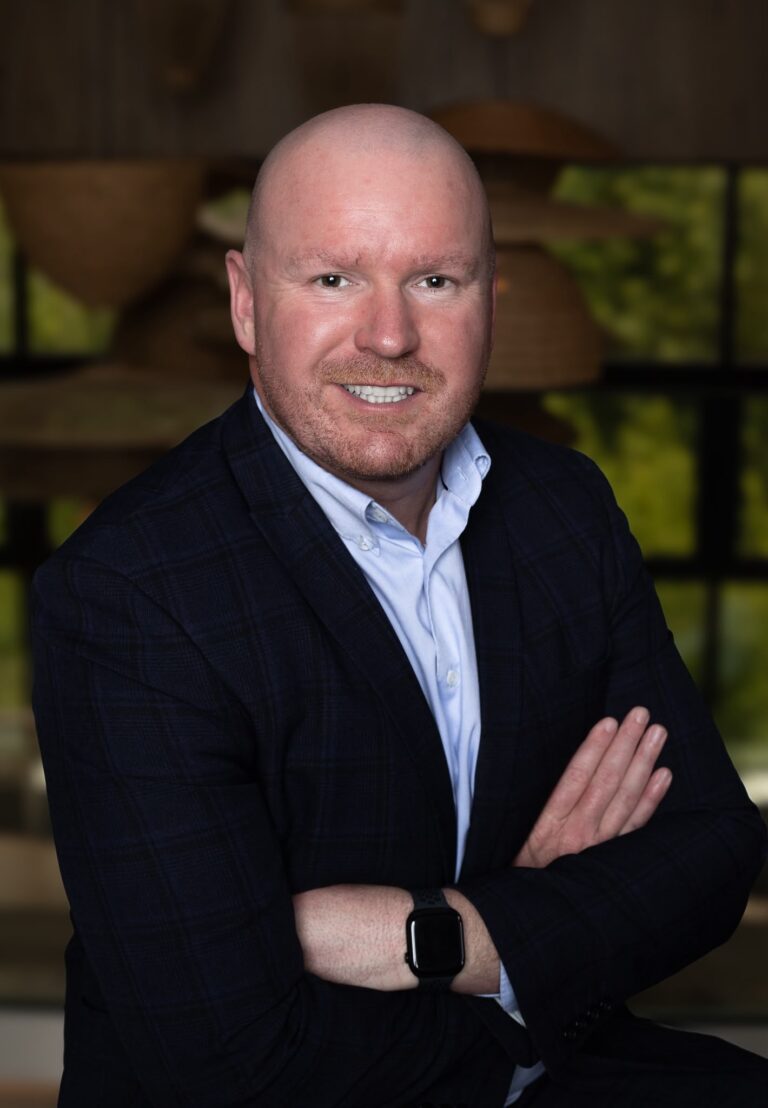
Director & Financial Planner
QualificationsQFA, RPA, SIA, BBS
A natural problem solver, Anthony thrives on finding the real challenge, working out how to resolve it, and putting the solution in place alongside the client.
Both calls are free and without obligation.
Three plain stages, at your pace. You can stop after any one of them.
Twenty minutes or so, by phone or video. You tell us what has been offered and what you are weighing up. Nothing is sold on that call, and nothing needs to be decided on it.
If it makes sense to go further, we go through the package documents, your pension entitlements, your outgoings and what cover you currently hold through work.
You get our findings written down, with the options set out clearly and what each one would mean for you. What you do with it is entirely your decision.
It starts with the short call. Nothing is sold on it.
The ones that come up most often when a package lands.
It is an estimate built from what you entered. The real number depends on how your service is counted, what your employer has offered above the statutory amount, and how that payment is treated. It is a useful thing to bring to a conversation.
Sometimes yes and often no. It turns on what your pension is worth to you at retirement and what you genuinely need the money for now. It is the most consequential decision in most packages and it cannot be undone, so it deserves more than an afternoon.
Longer than most people assume. We work back from what your household actually spends, what other income exists, and a realistic view of how long finding the next role takes rather than an optimistic one.
It is often worth looking at, and it depends on your age, what you already hold and what you need to live on in the meantime. We look at it beside everything else rather than in isolation.
Nothing. It is a no-obligation, free discovery call. If we go further than that, we set out clearly what the work involves and what it costs before you commit to anything.
A different question? Ask us directly and we will give you a straight answer.
Bring the figure you calculated and whatever the employer has put in writing. We will tell you plainly what we think, and what we would look at first.
Or email [email protected]
APFM Limited, trading as Pathway Financial Management, is regulated by the Central Bank of Ireland. Registered in Ireland No. 759815. Directors: Paul McGrane, Anthony Richardson.
Warning: The value of your investment may go down as well as up.
Warning: These figures are estimates only. They are not a reliable guide to future performance of this investment.
This page is general information about financial planning. It is not personal financial advice and does not take account of your own circumstances. Tax treatment depends on individual circumstances and may change.